Q3 2026 Venture Capital in Africa Report
This series provides an exclusive look at the latest trends in African Venture Capital, offering insights into regional dynamics, sector-specific shifts, and the key areas driving investment across the continent during Q3 2026.
Question for the Research Team?
For questions or comments on this publication, please contact research@avca.africa.
Read the Public Report
Download the Report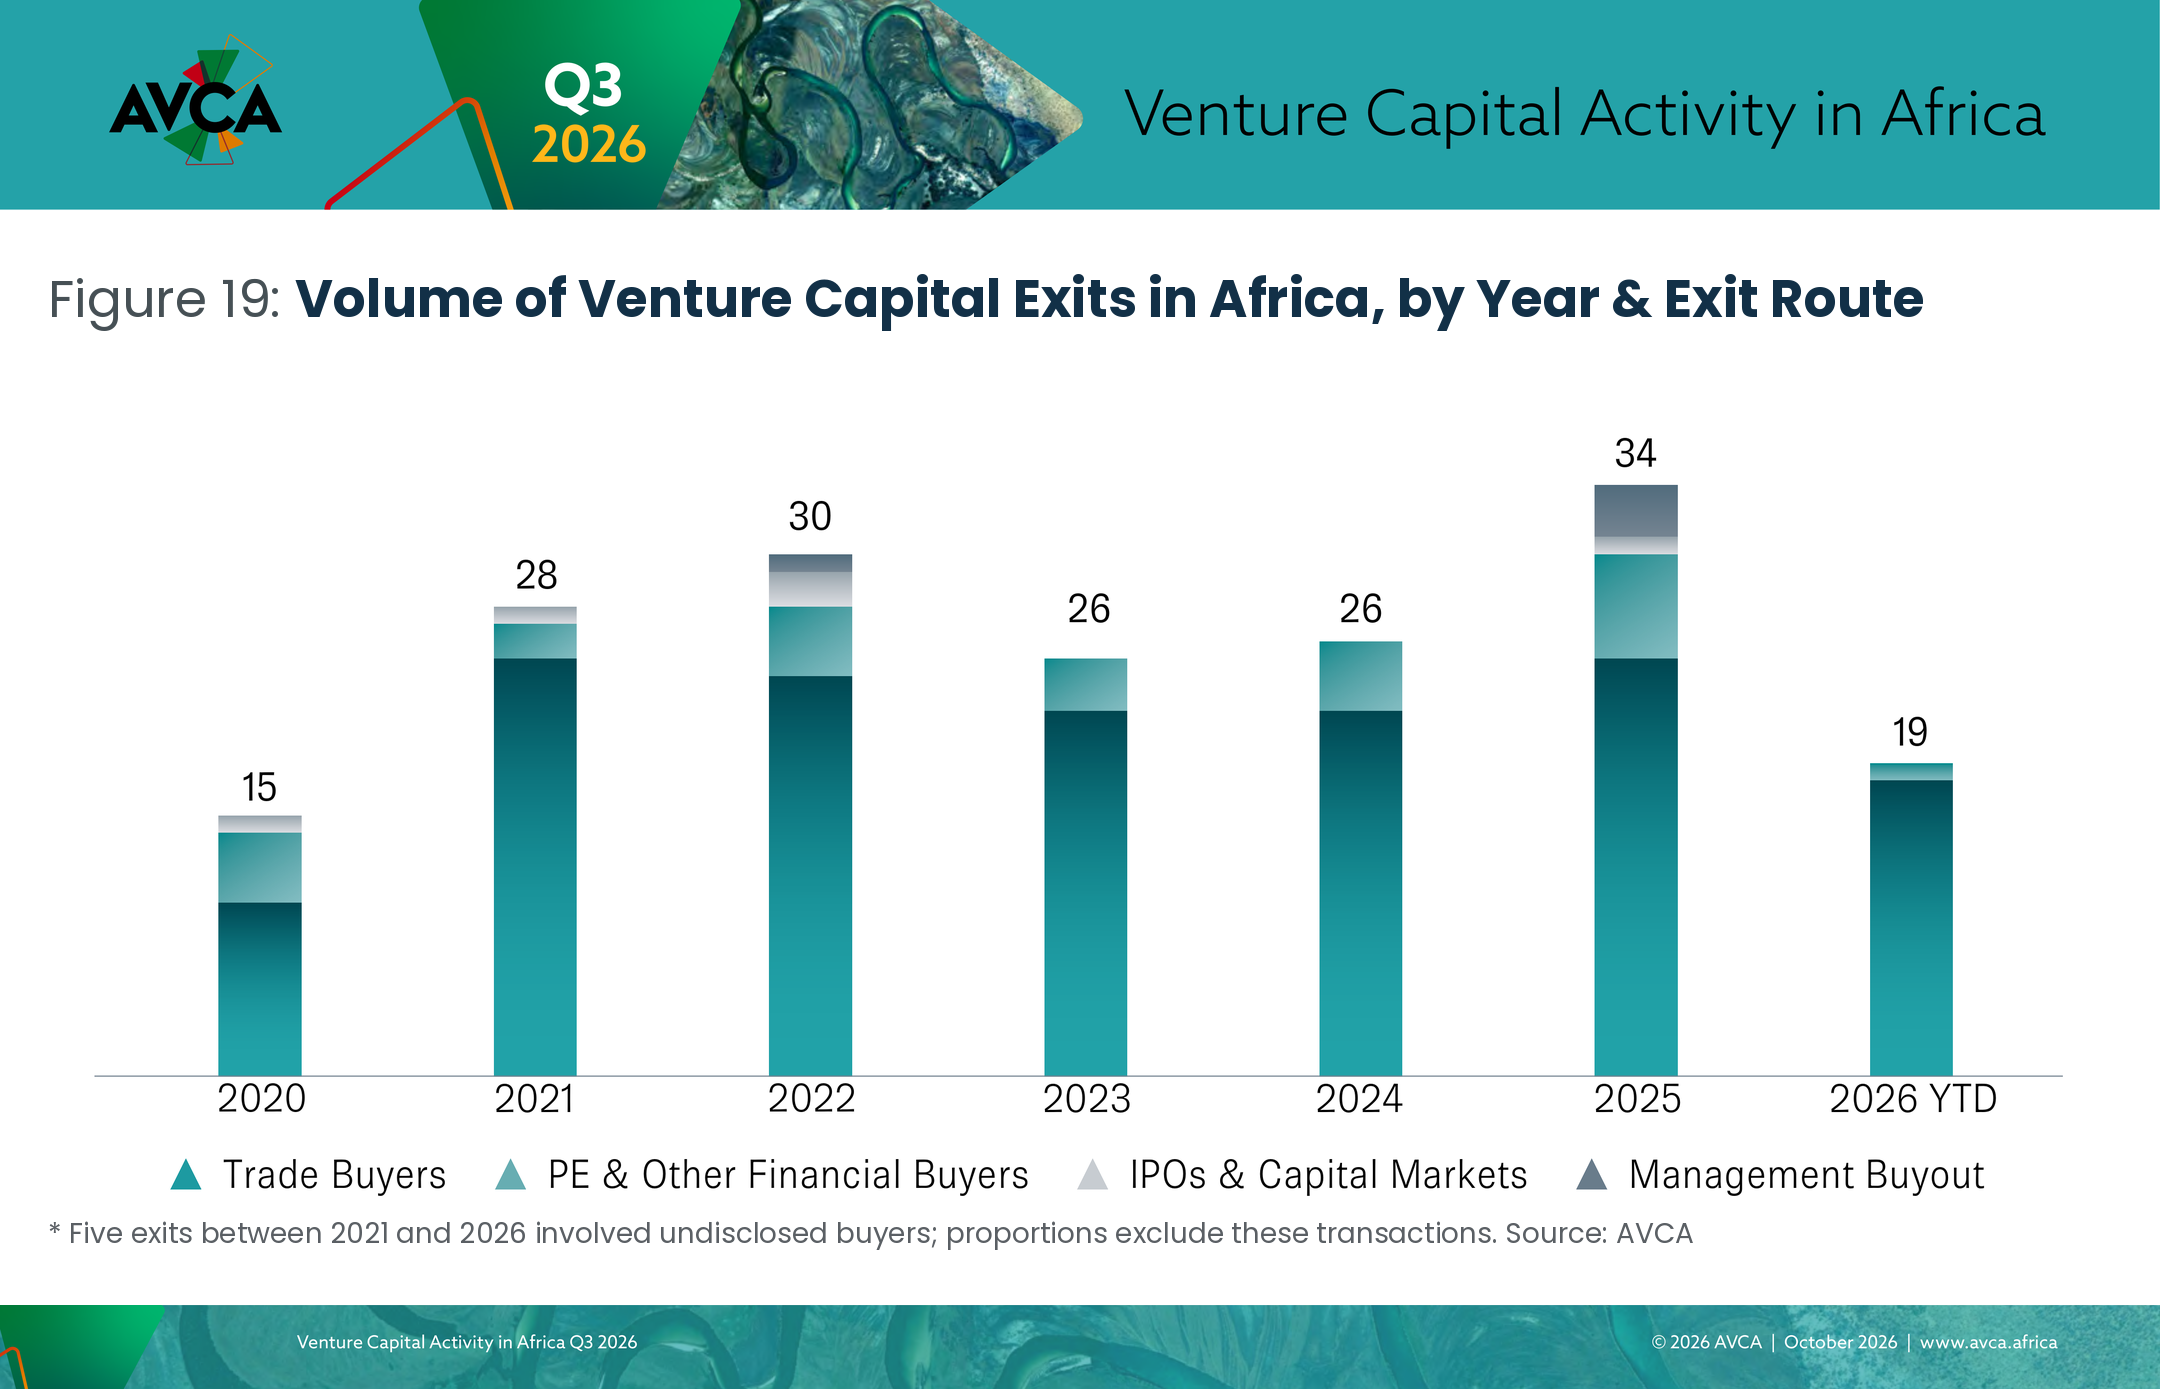
Key Findings:
-
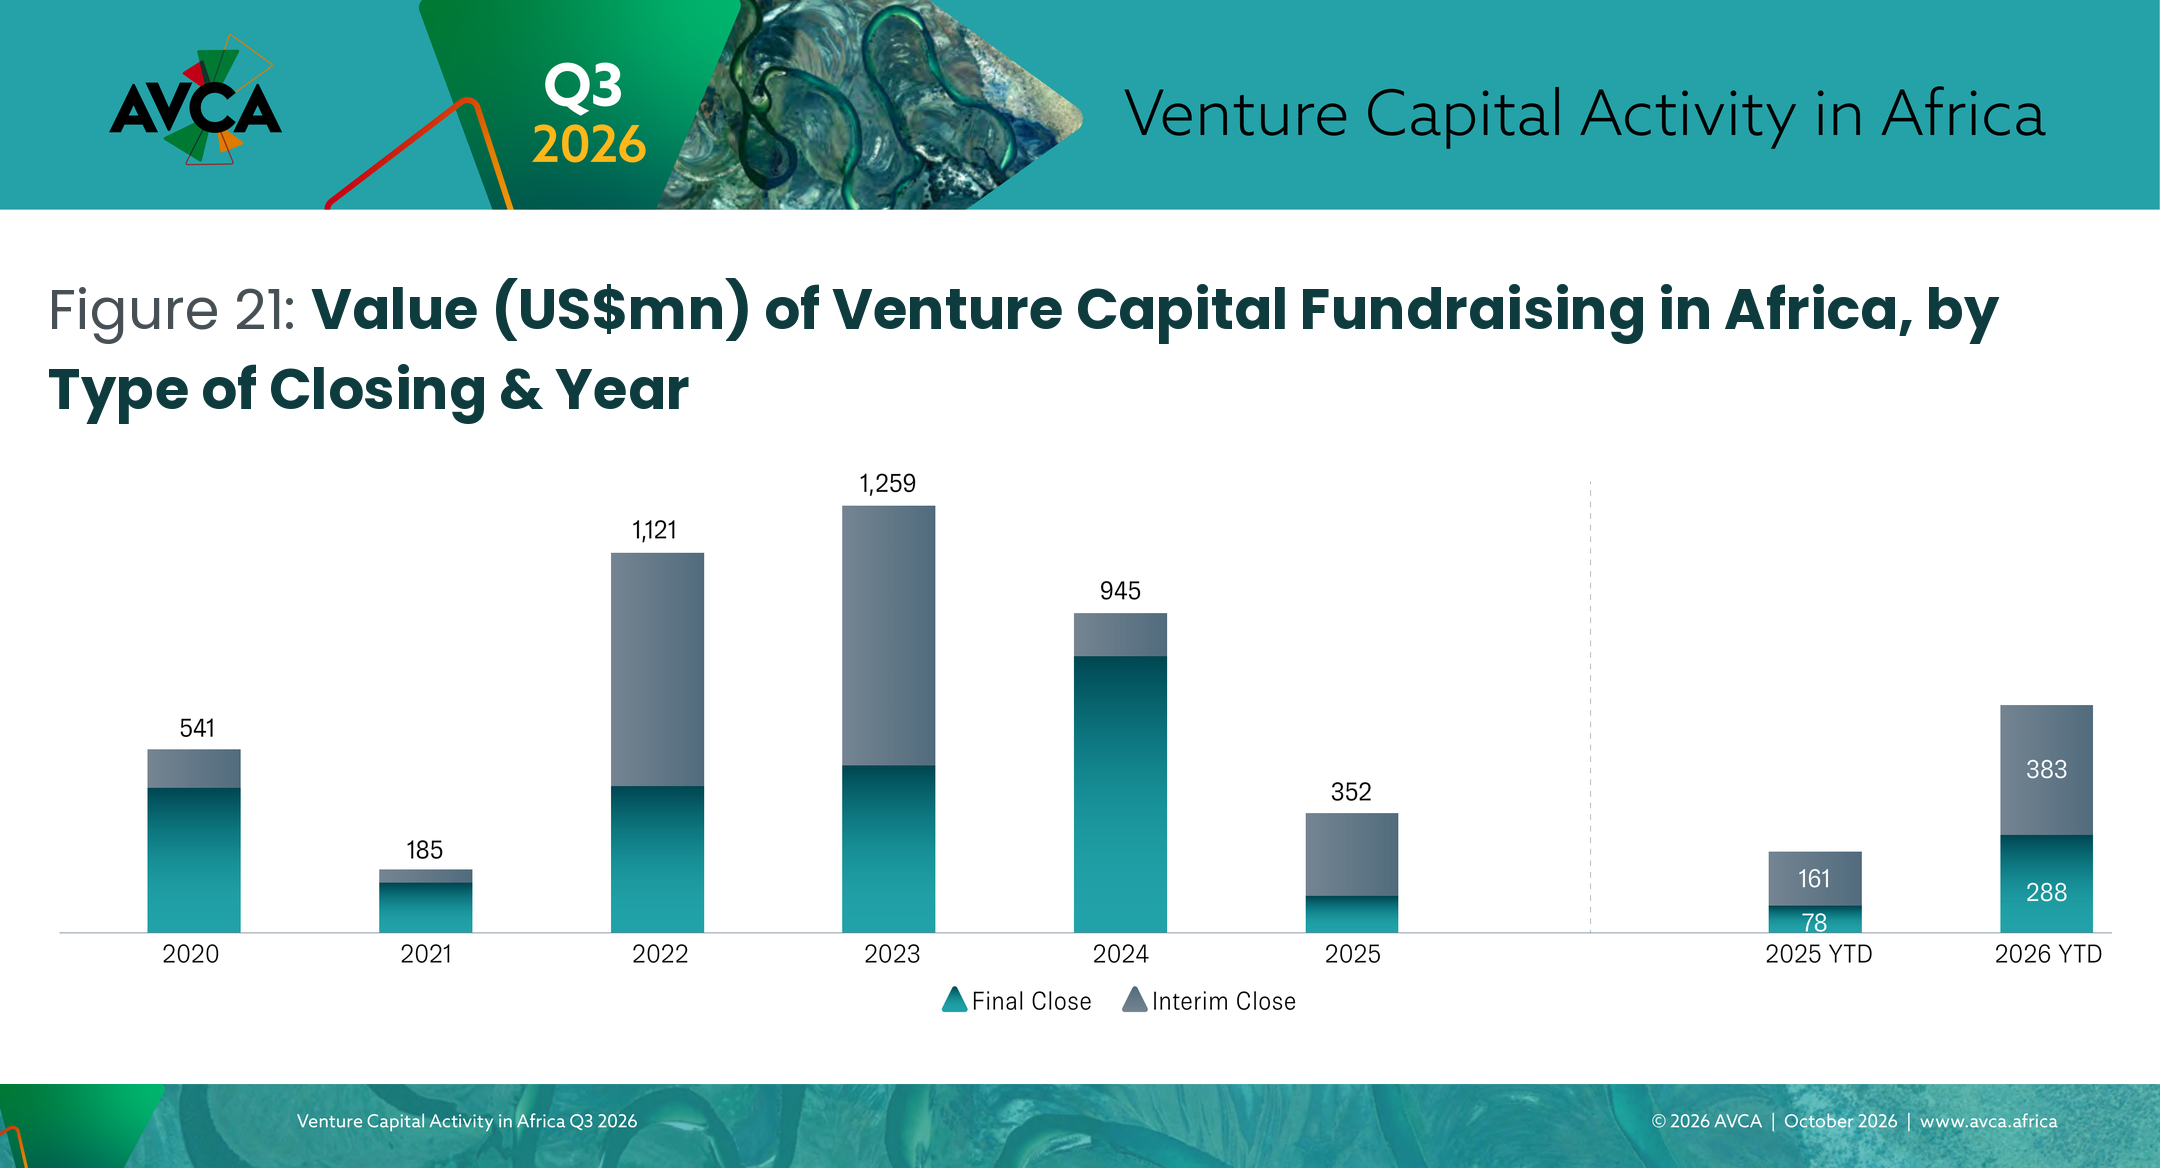
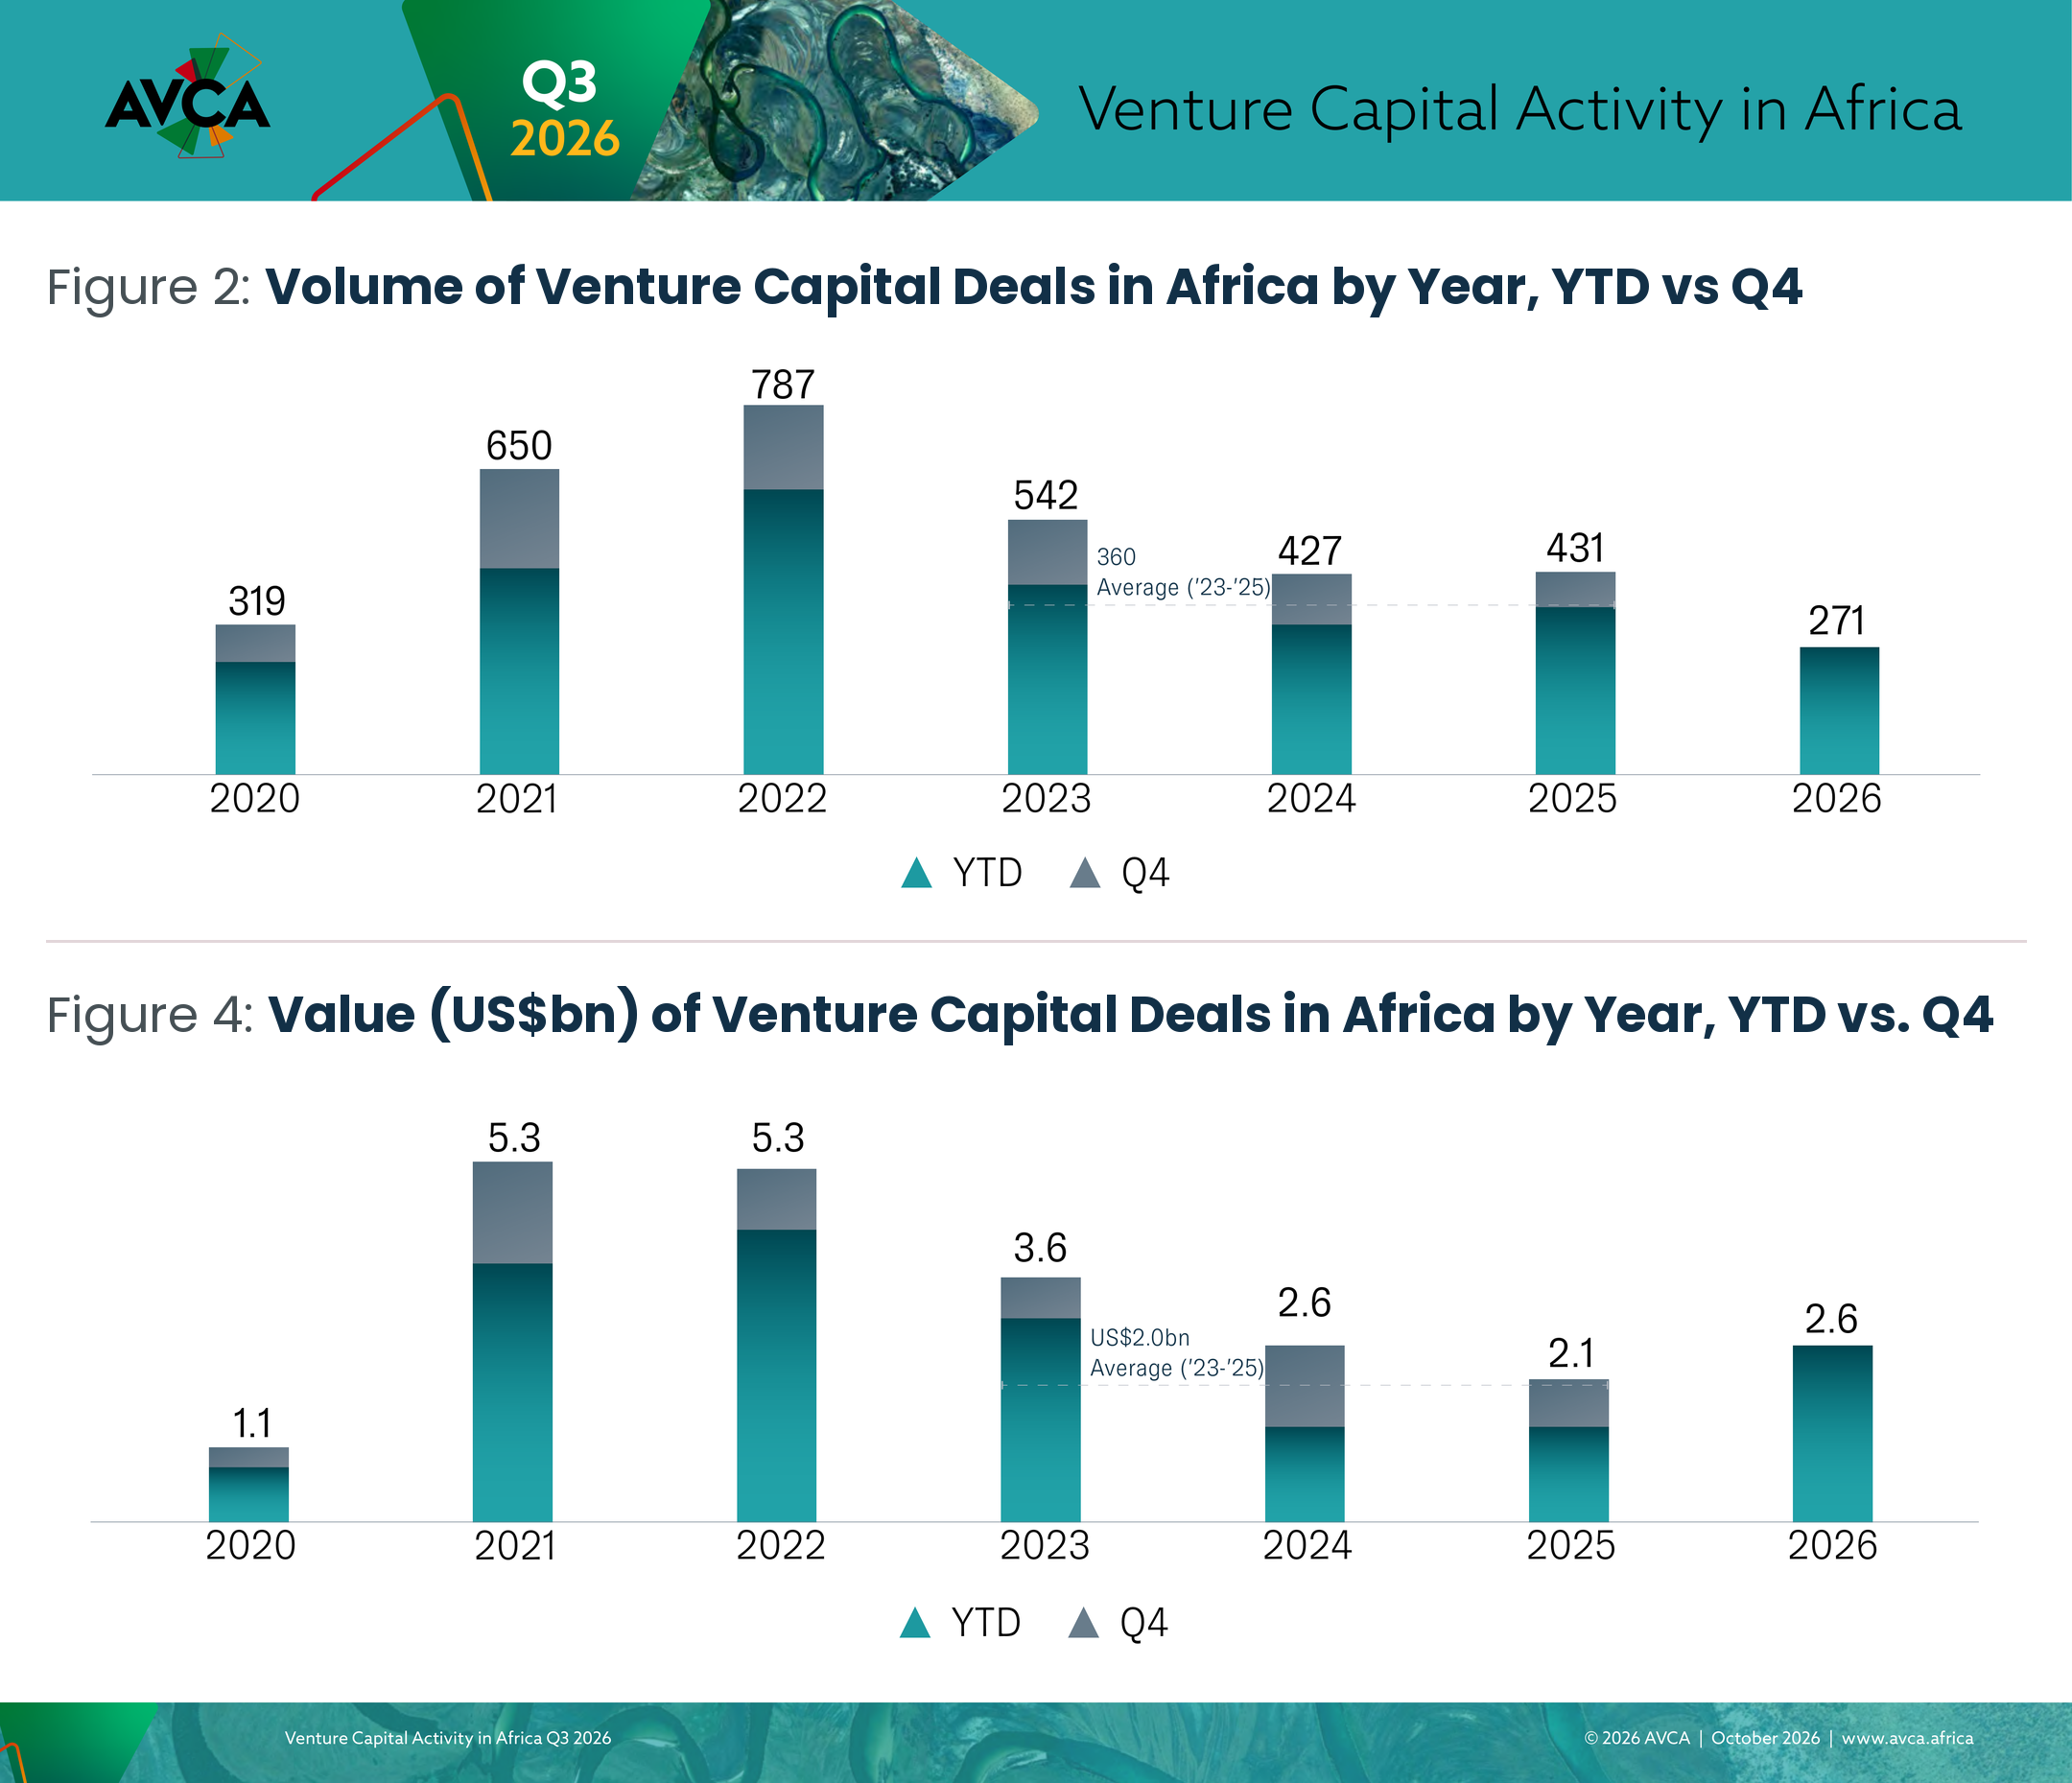
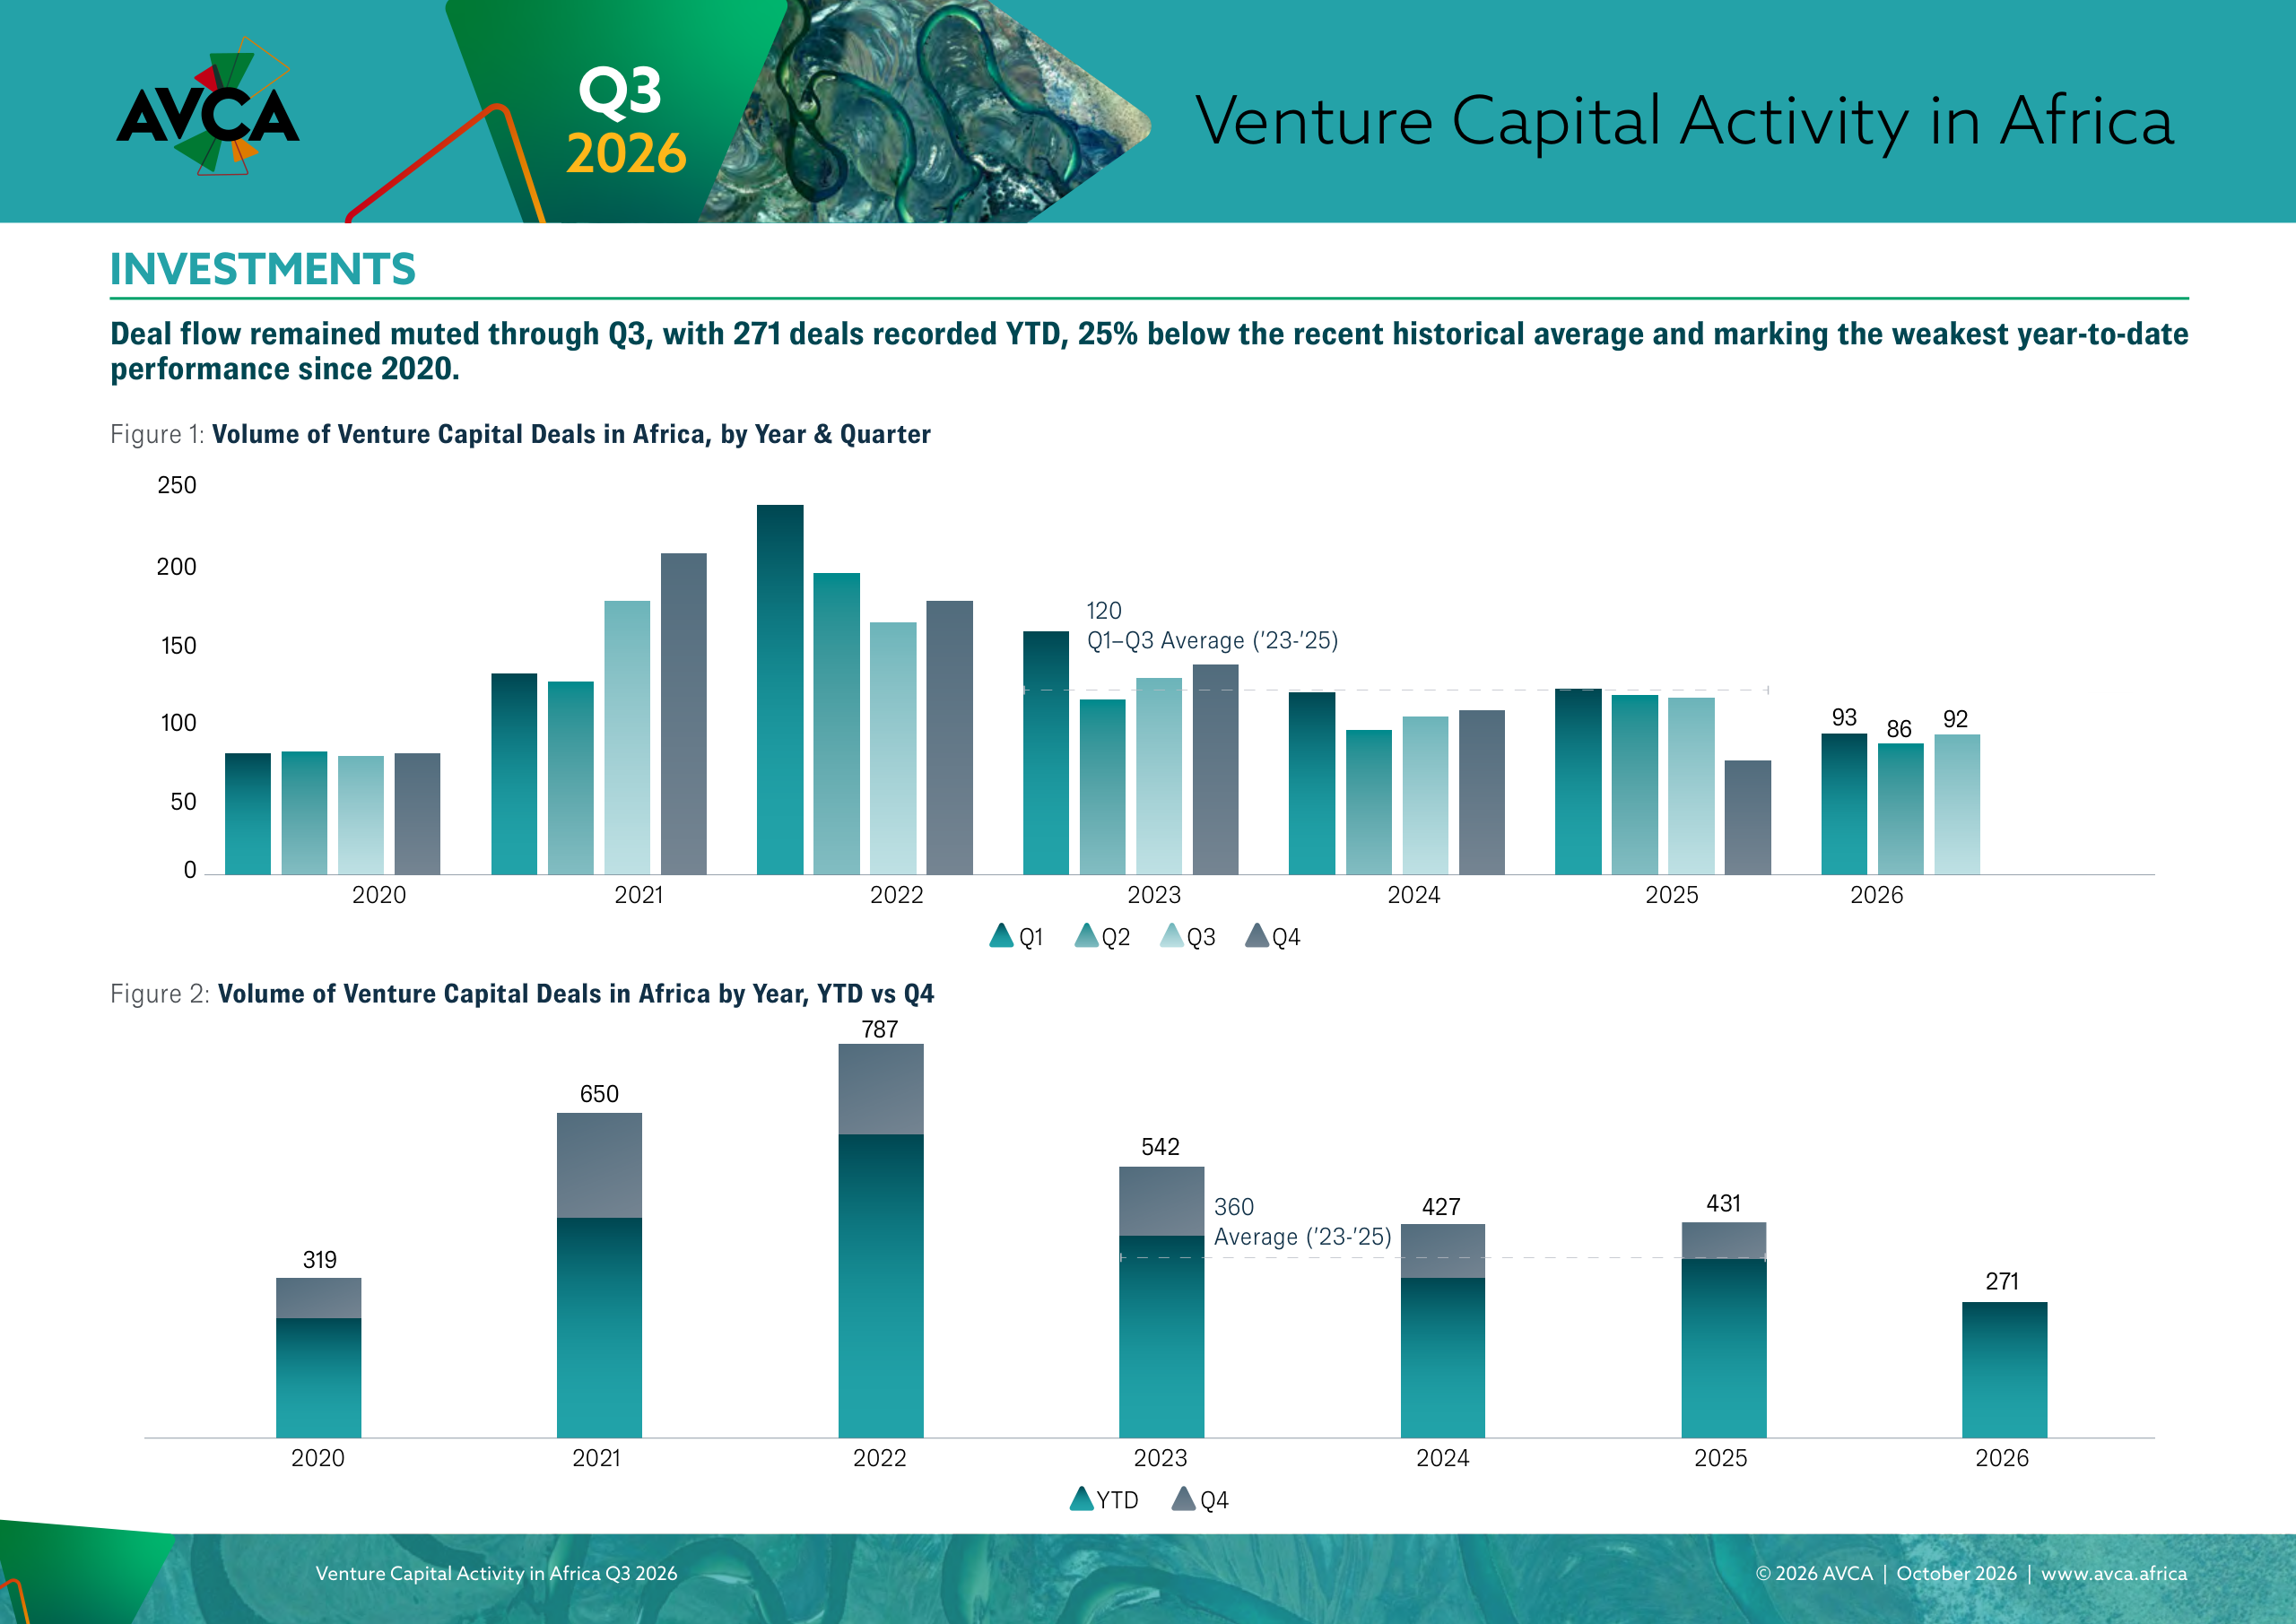
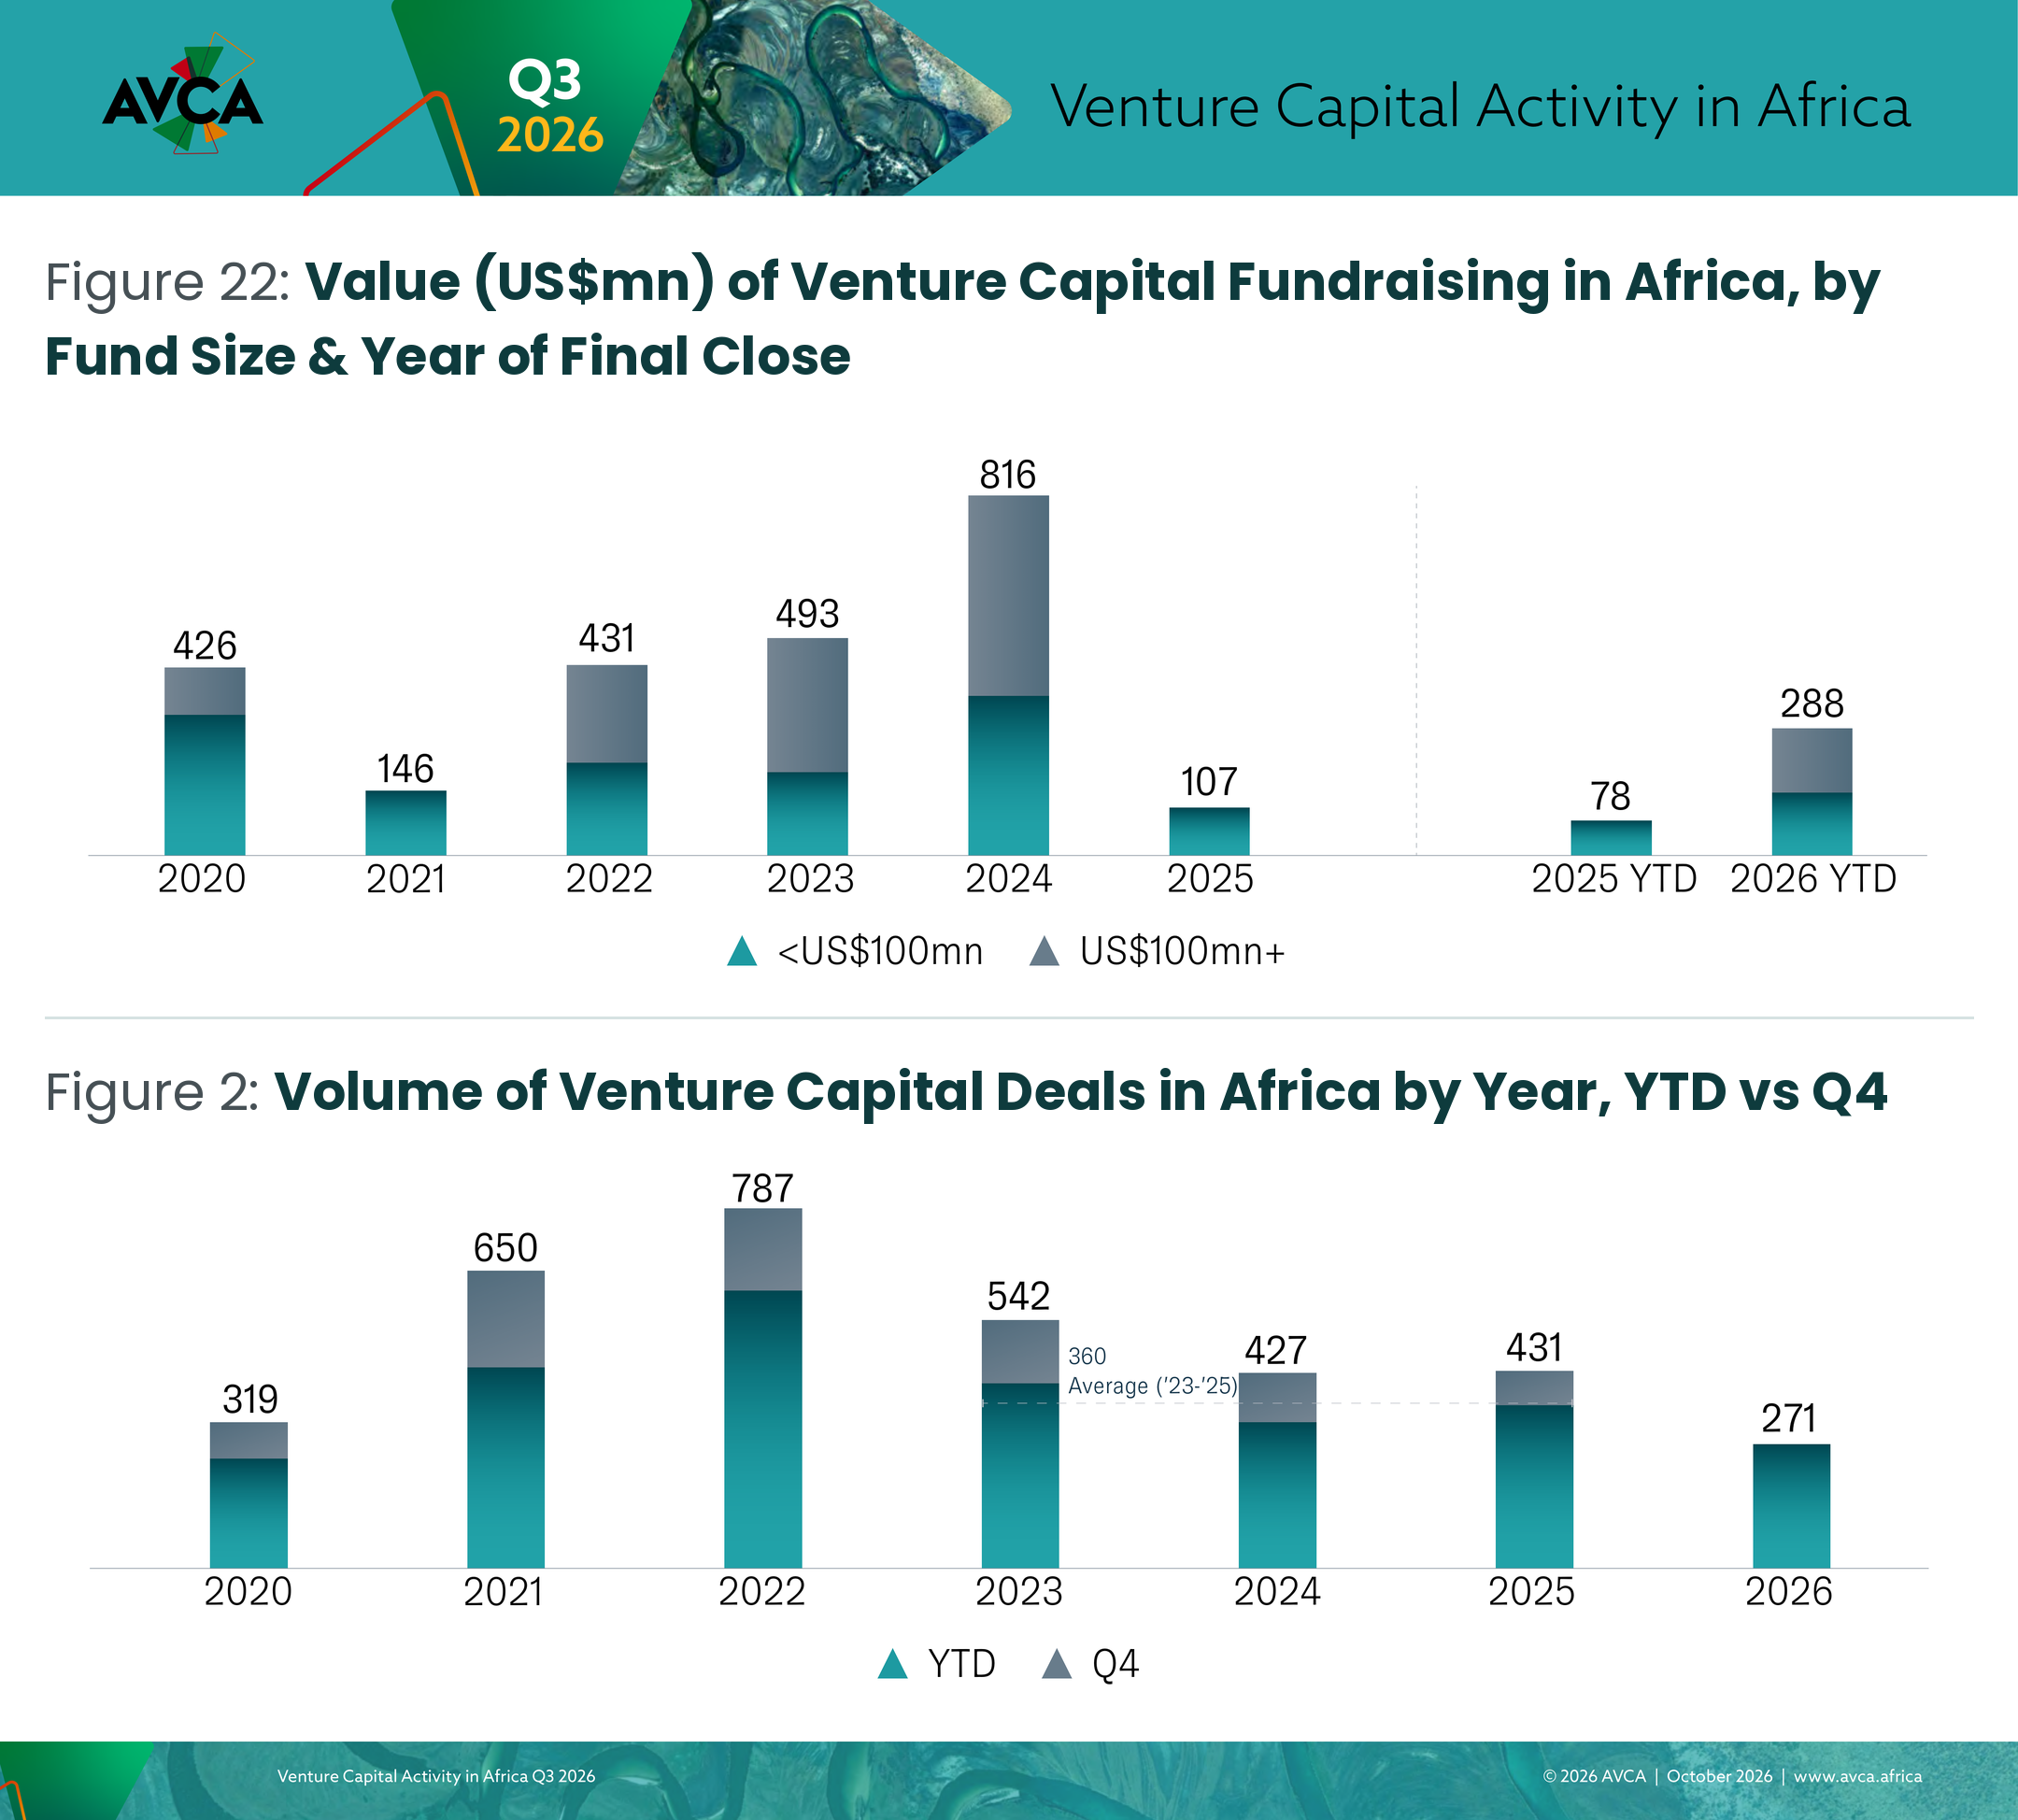
Capital Raising Recovered Faster Than Dealmaking: Fundraising accelerated through Q3 2026, with interim and final closes surpassing prior-year levels, signalling continued investor confidence in African VC. Yet investment activity remained subdued, with just 271 deals recorded YTD, the weakest performance since 2020 and well below recent historical averages.
-
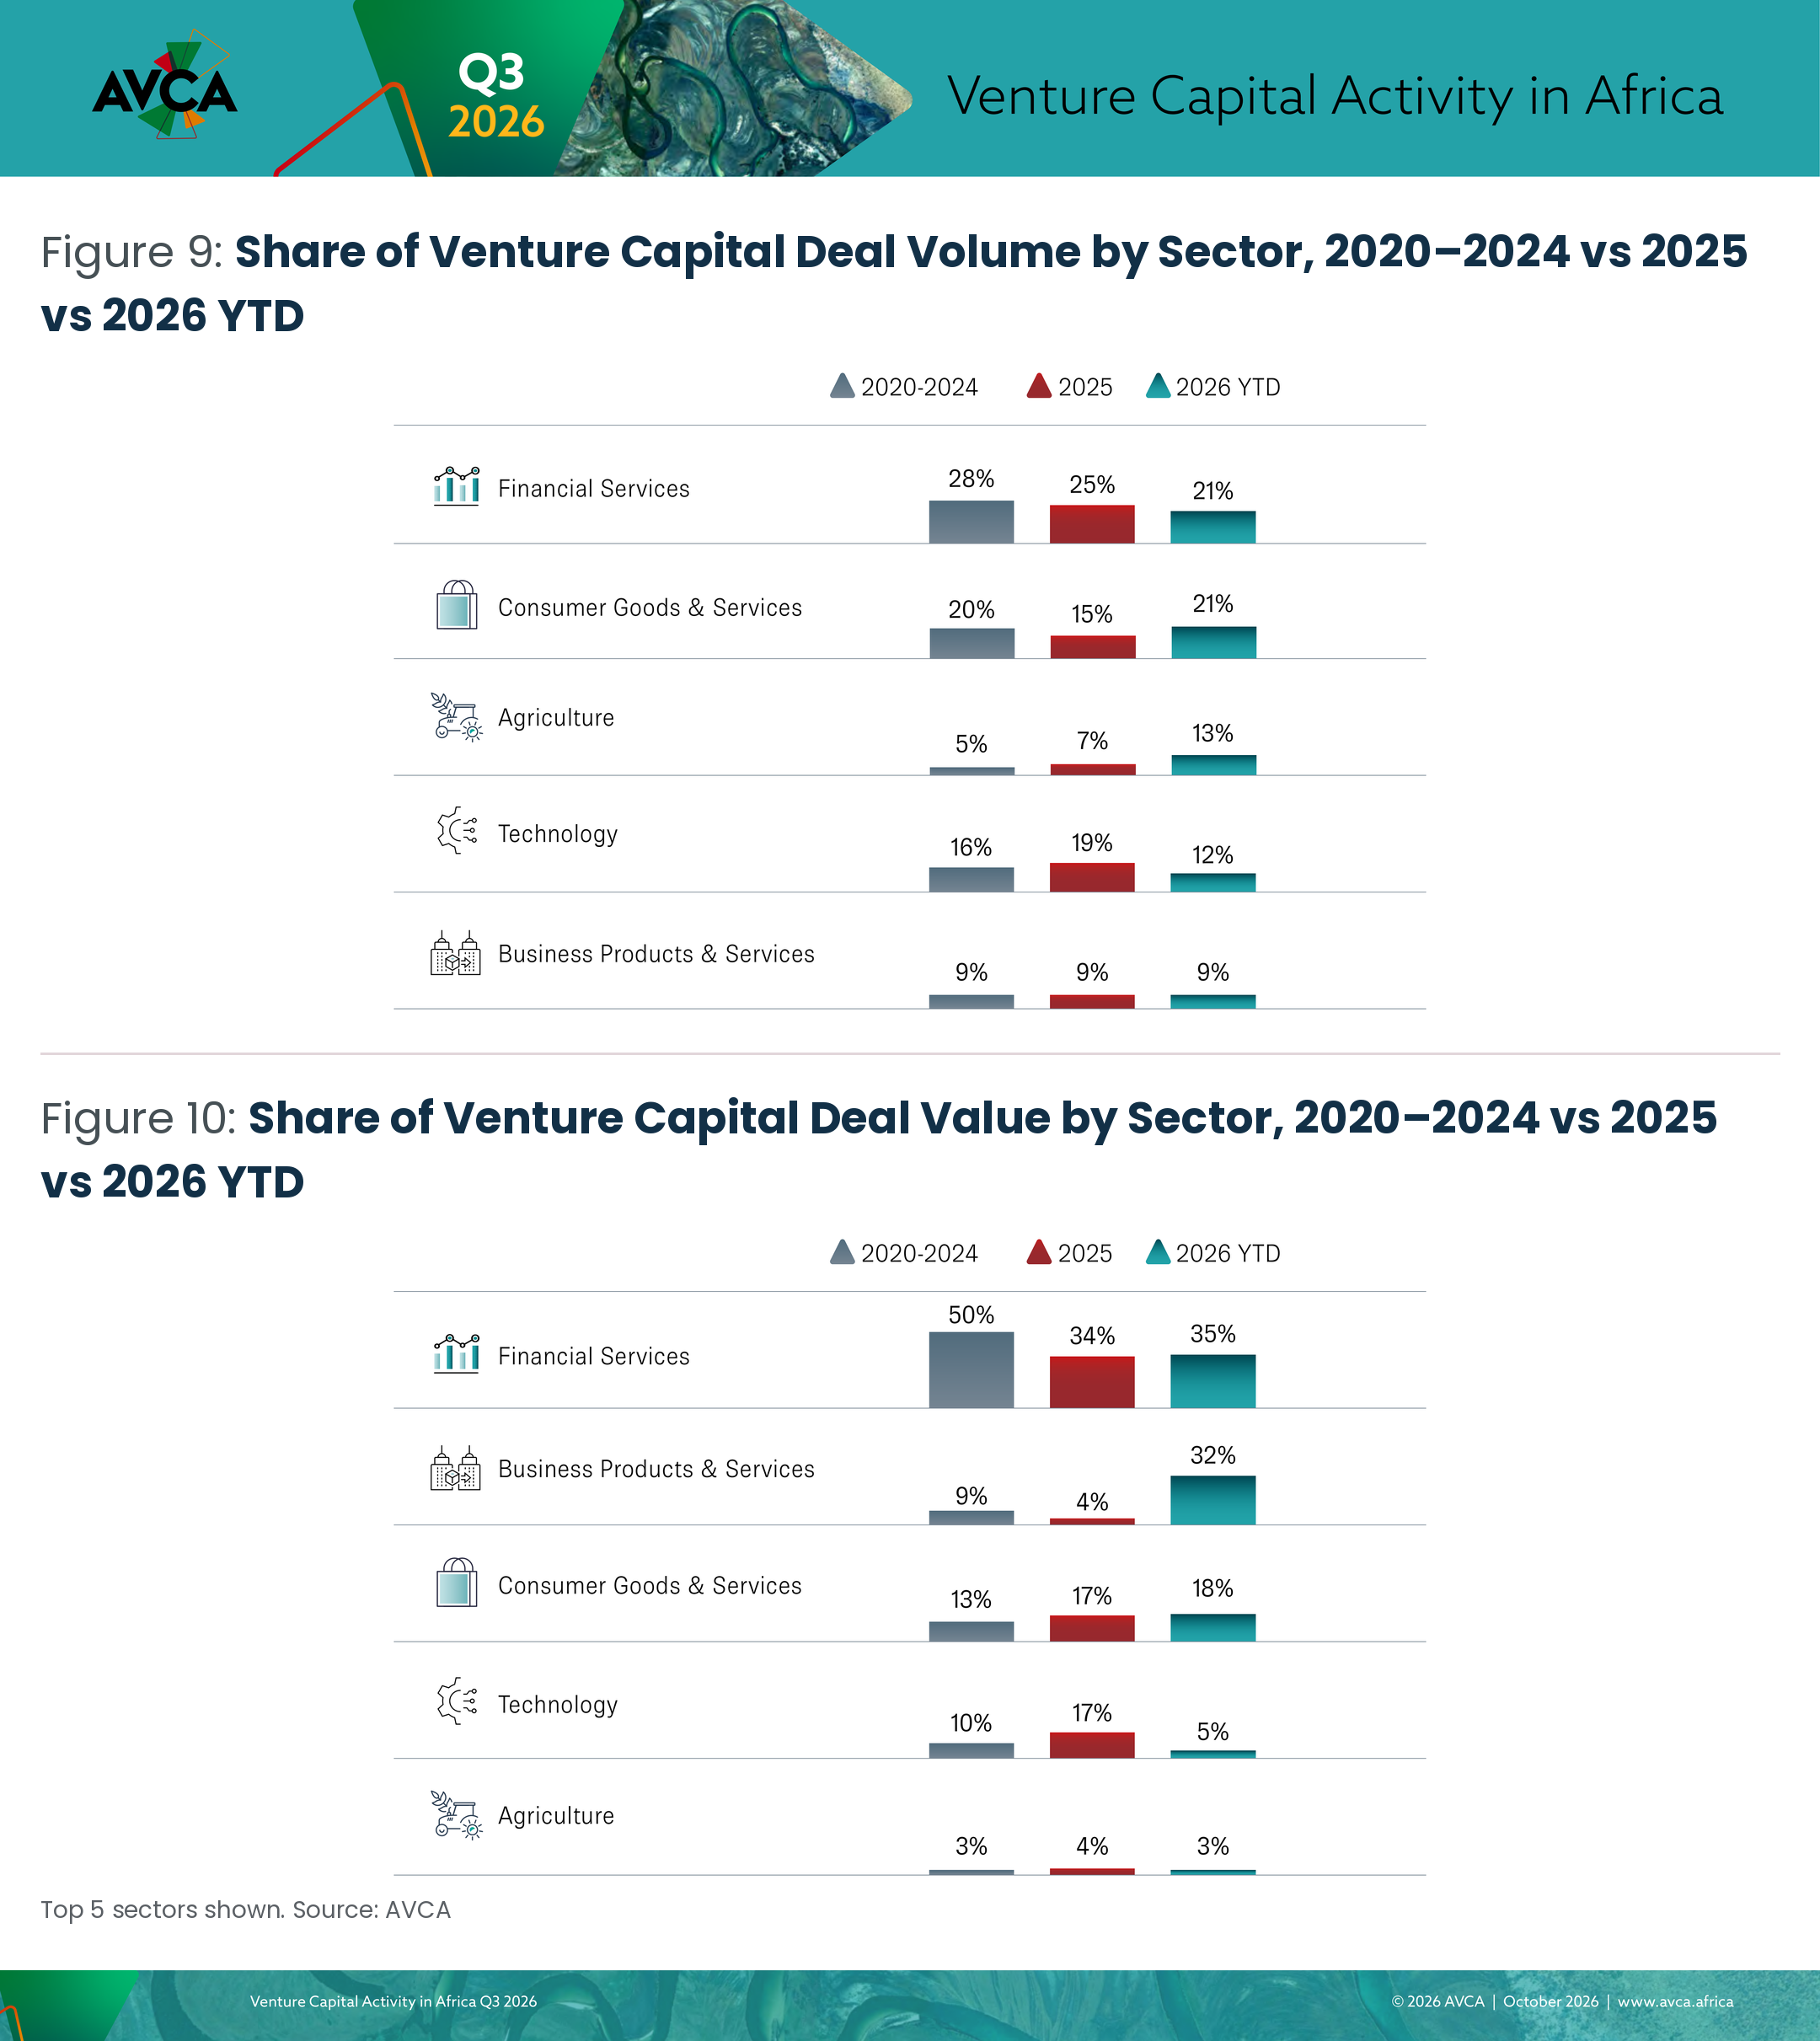
Investors Continued to Prioritise Scale: Late-stage funding surged while seed-stage activity remained under pressure, reflecting a continued preference for proven business models and businesses with demonstrated traction.
-
Megadeals Drove Funding Growth: Venture funding reached US$2.6bn despite softer deal activity. However, four megadeals accounted for roughly two-thirds of total capital deployed, highlighting the concentration behind the market's recovery.
-
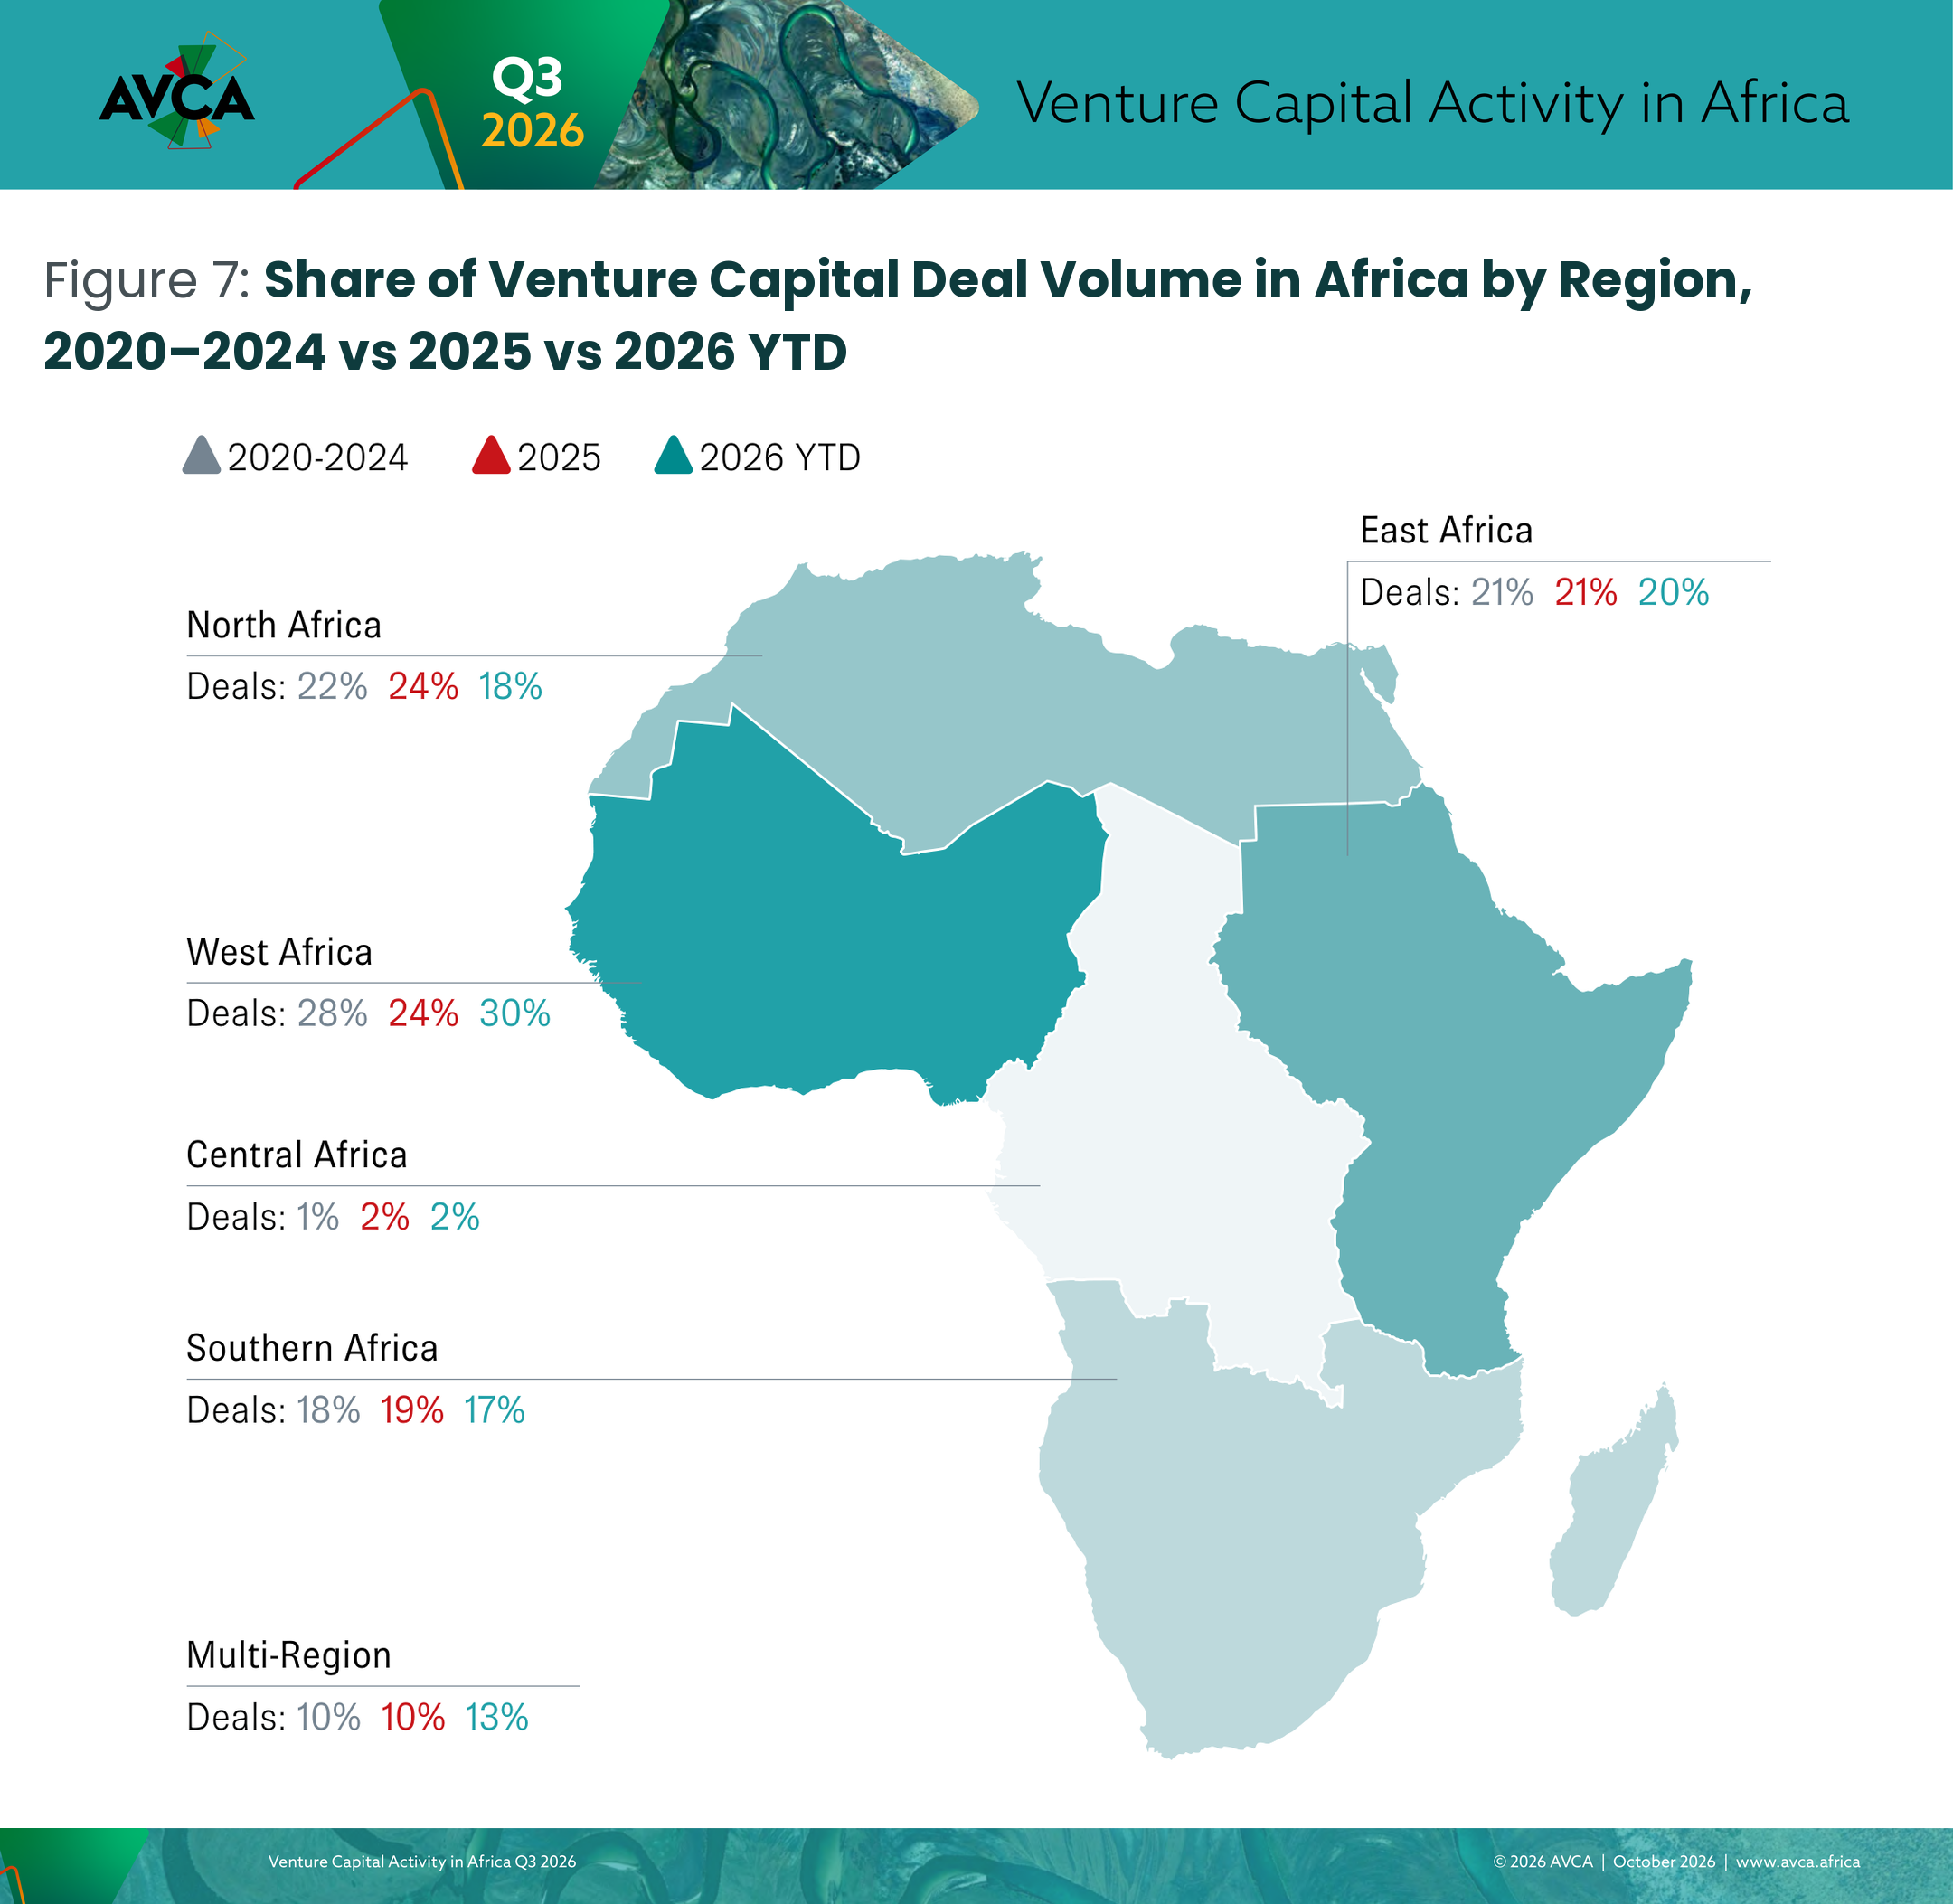
Investors Backed Pan-African Growth: Multi-Region companies secured 70% of total funding value, supported by large raises such as Moove's US$250mn Series C, reinforcing investor appetite for businesses capable of scaling across markets.
-
Venture Debt Reached New Highs: A record 65 venture debt transactions underscored the growing role of alternative financing alongside traditional equity capital.
-
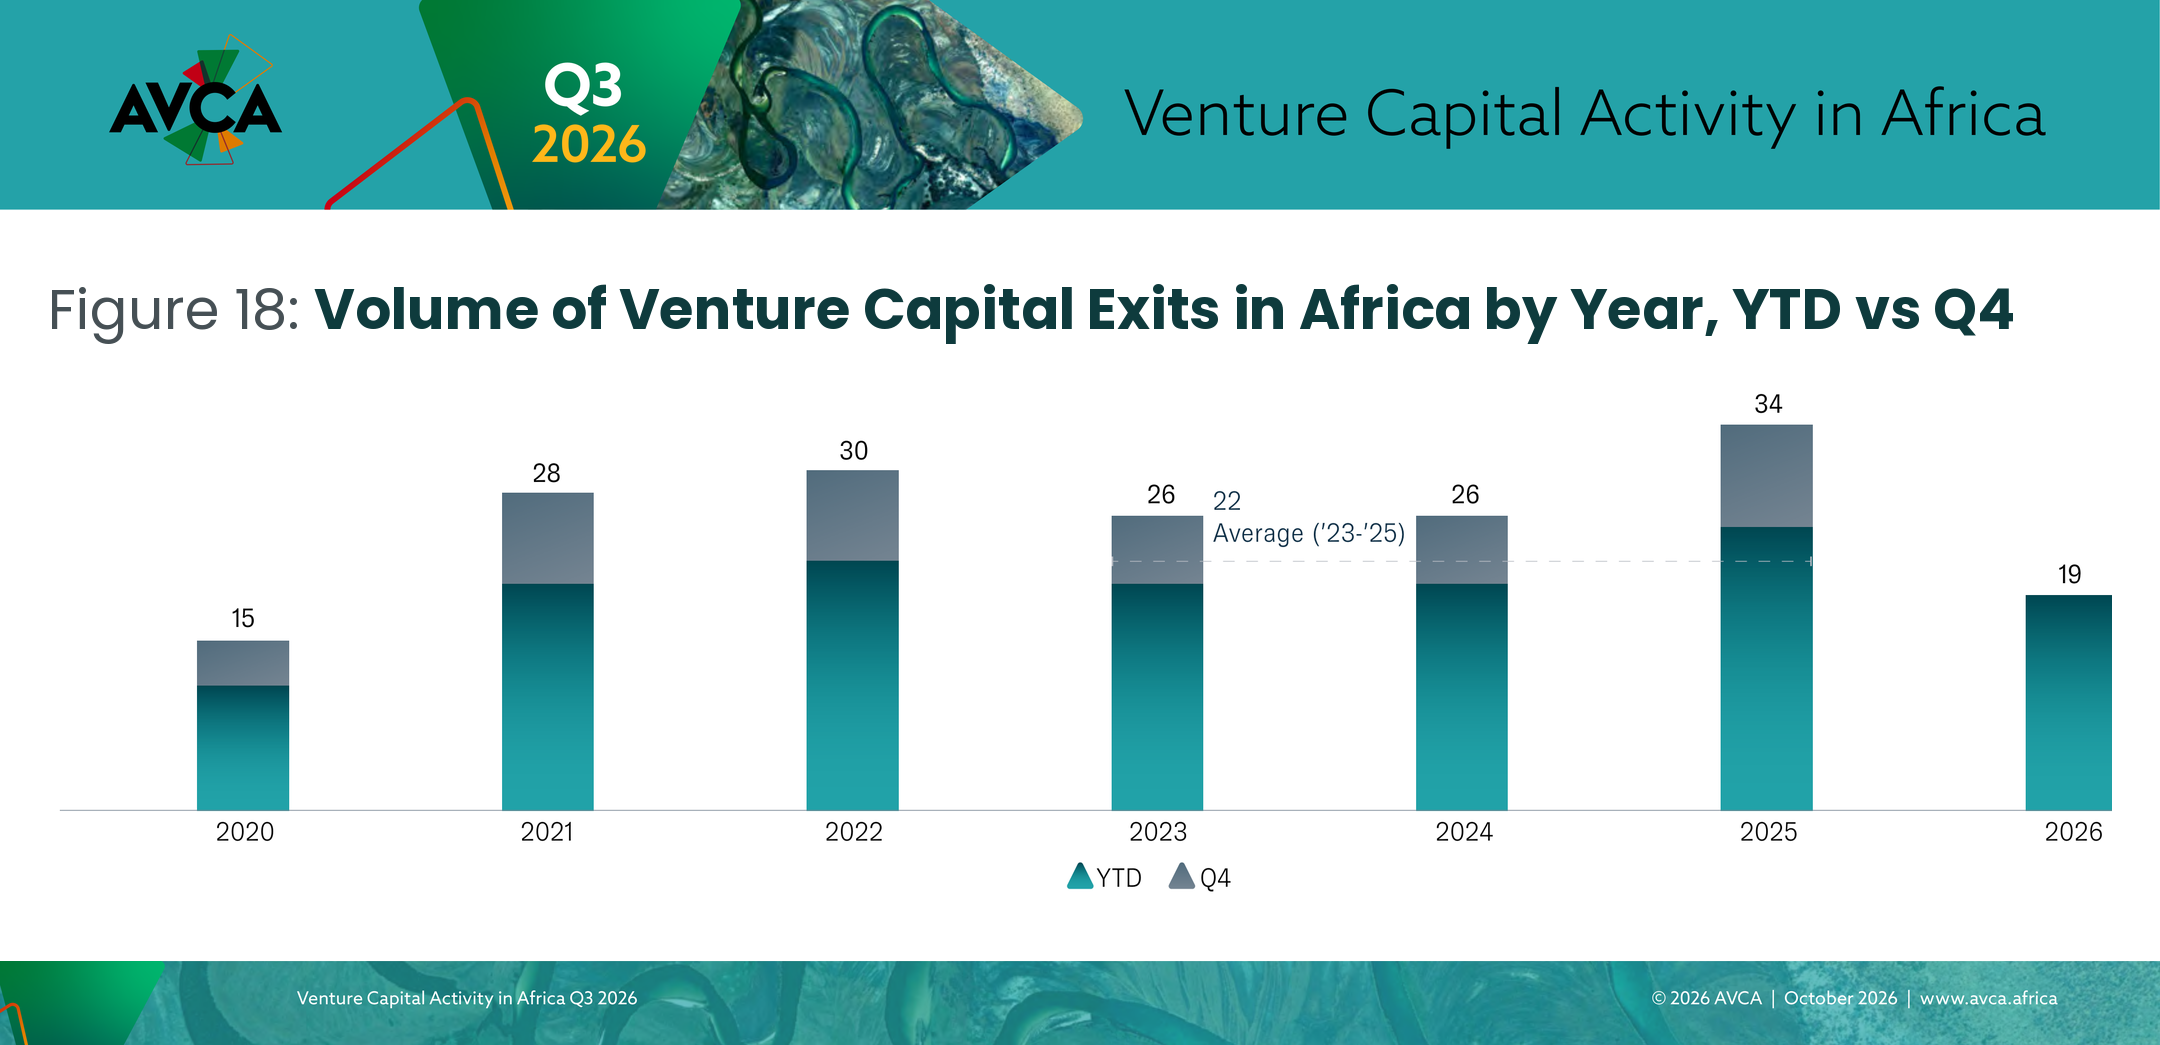
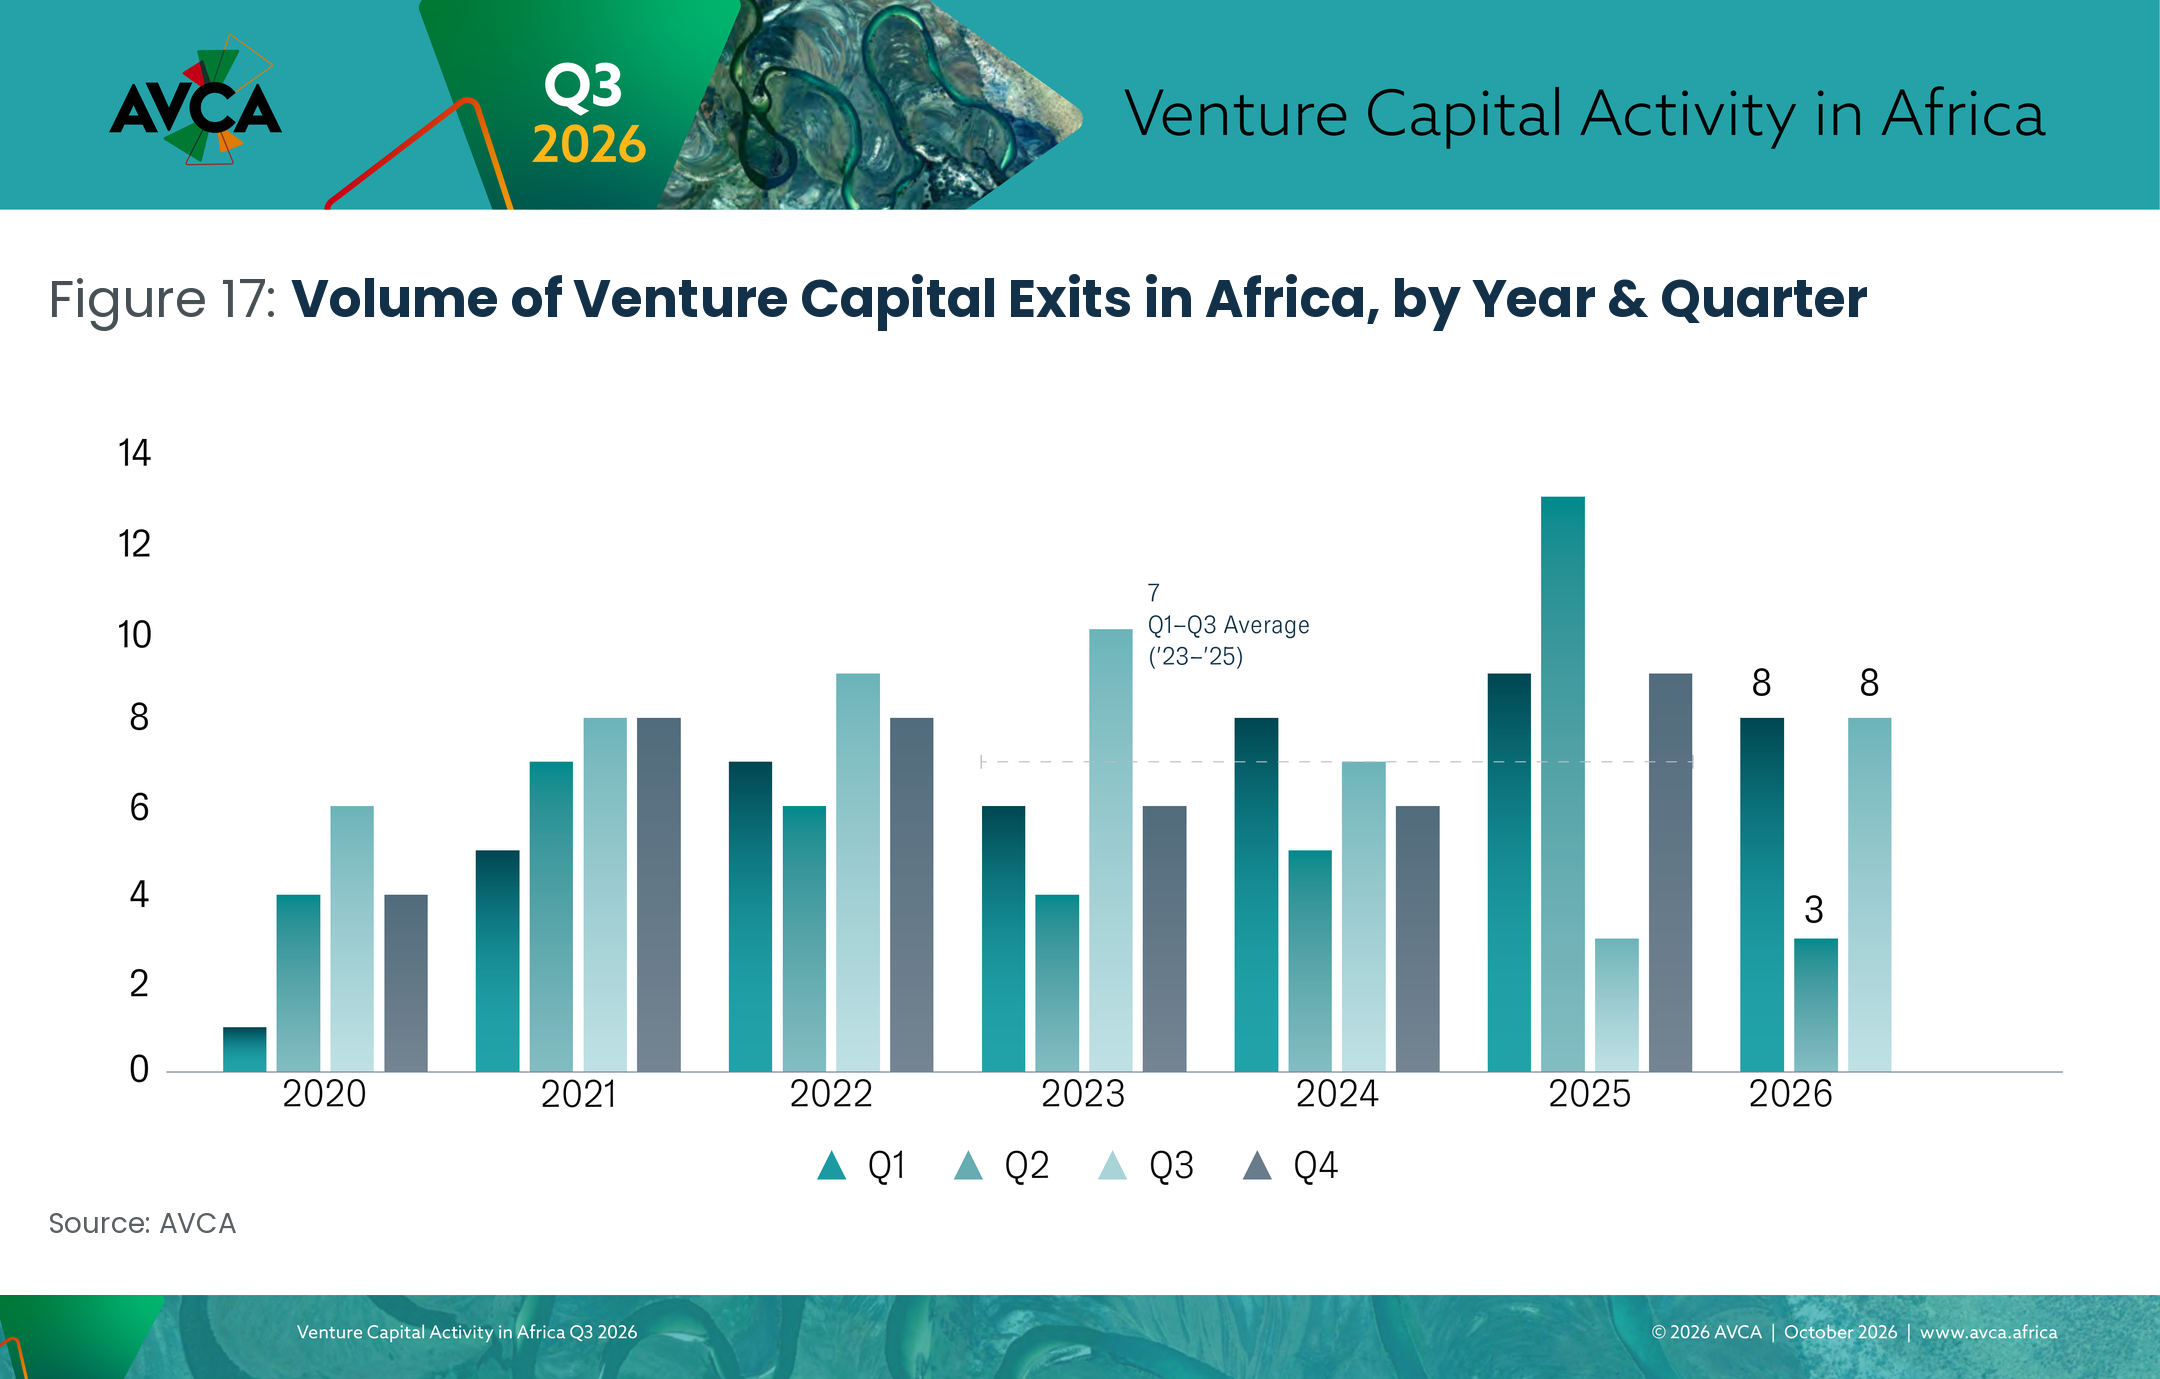
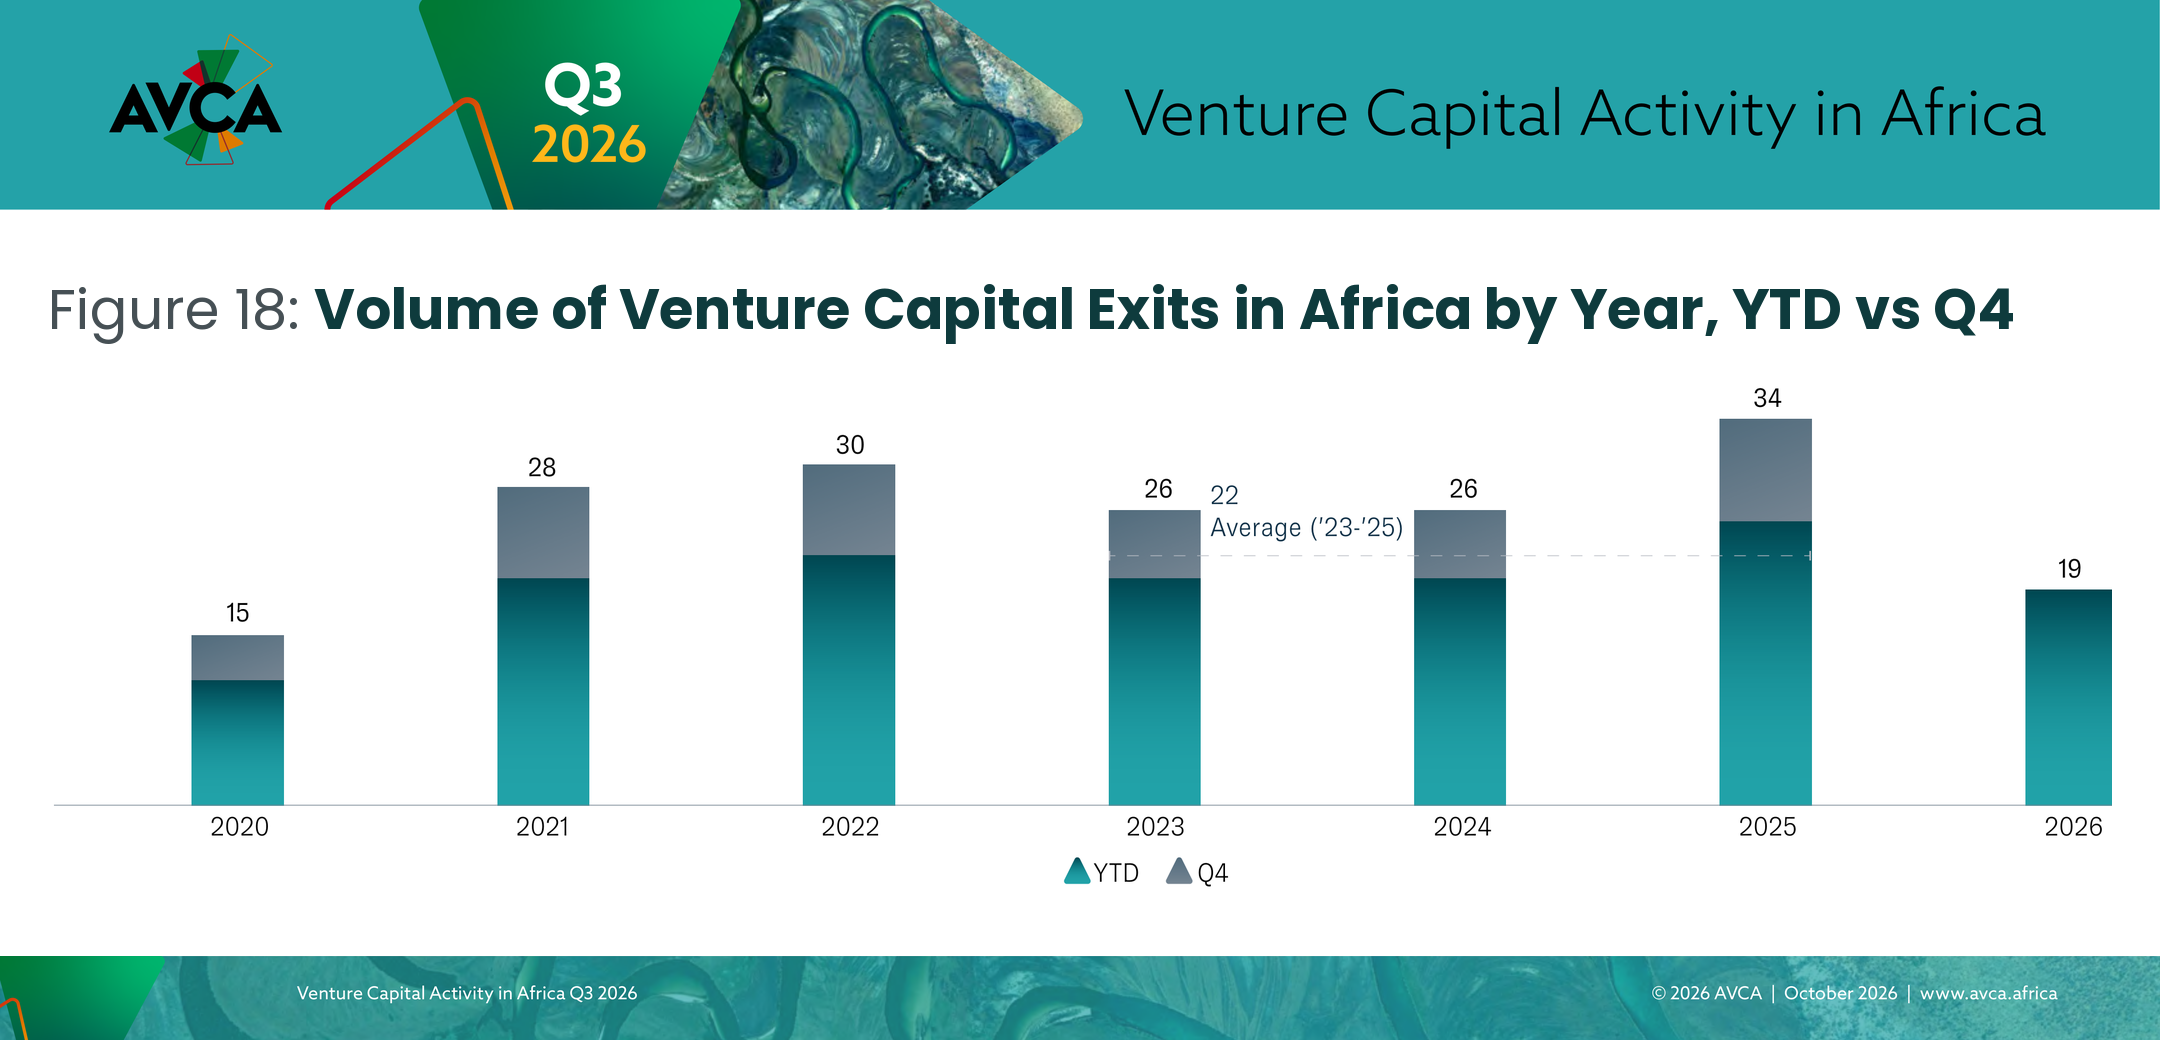
Strategic Acquisitions Anchored a Stable Exit Market: Trade buyers represented nearly 90% of exits in 2026 YTD, while median holding periods remained close to three years, as corporate acquisitions continue to provide a consistent liquidity pathway.
Download our shareable graphics and share the key findings with your network.
Share On: